 Voxly Vision
Does this apply to me?
BCOBS 2 applies to firms providing retail banking services, covering:
- Banks and building societies
- Current account and savings account communications
- Rate information in promotions and summary boxes
It is enforced by the FCA and sits alongside the Consumer Duty, which raised the bar on whether communications actually help customers understand and act.
Key rules
The main requirements:
- Clear, fair and not misleading communications and promotions.
- Show rates clearly — in promotions and the savings summary box.
- Help customers act — e.g. understand whether to switch.
- Consistency with the Consumer Duty understanding outcome.
Common breaches
Where banks fall short:
- Generic mass mailings that don't explain the customer's own rate.
- Poorly communicated rate changes.
- Failing to prompt or enable switching.
How Voxly Vision checks an ad against this code
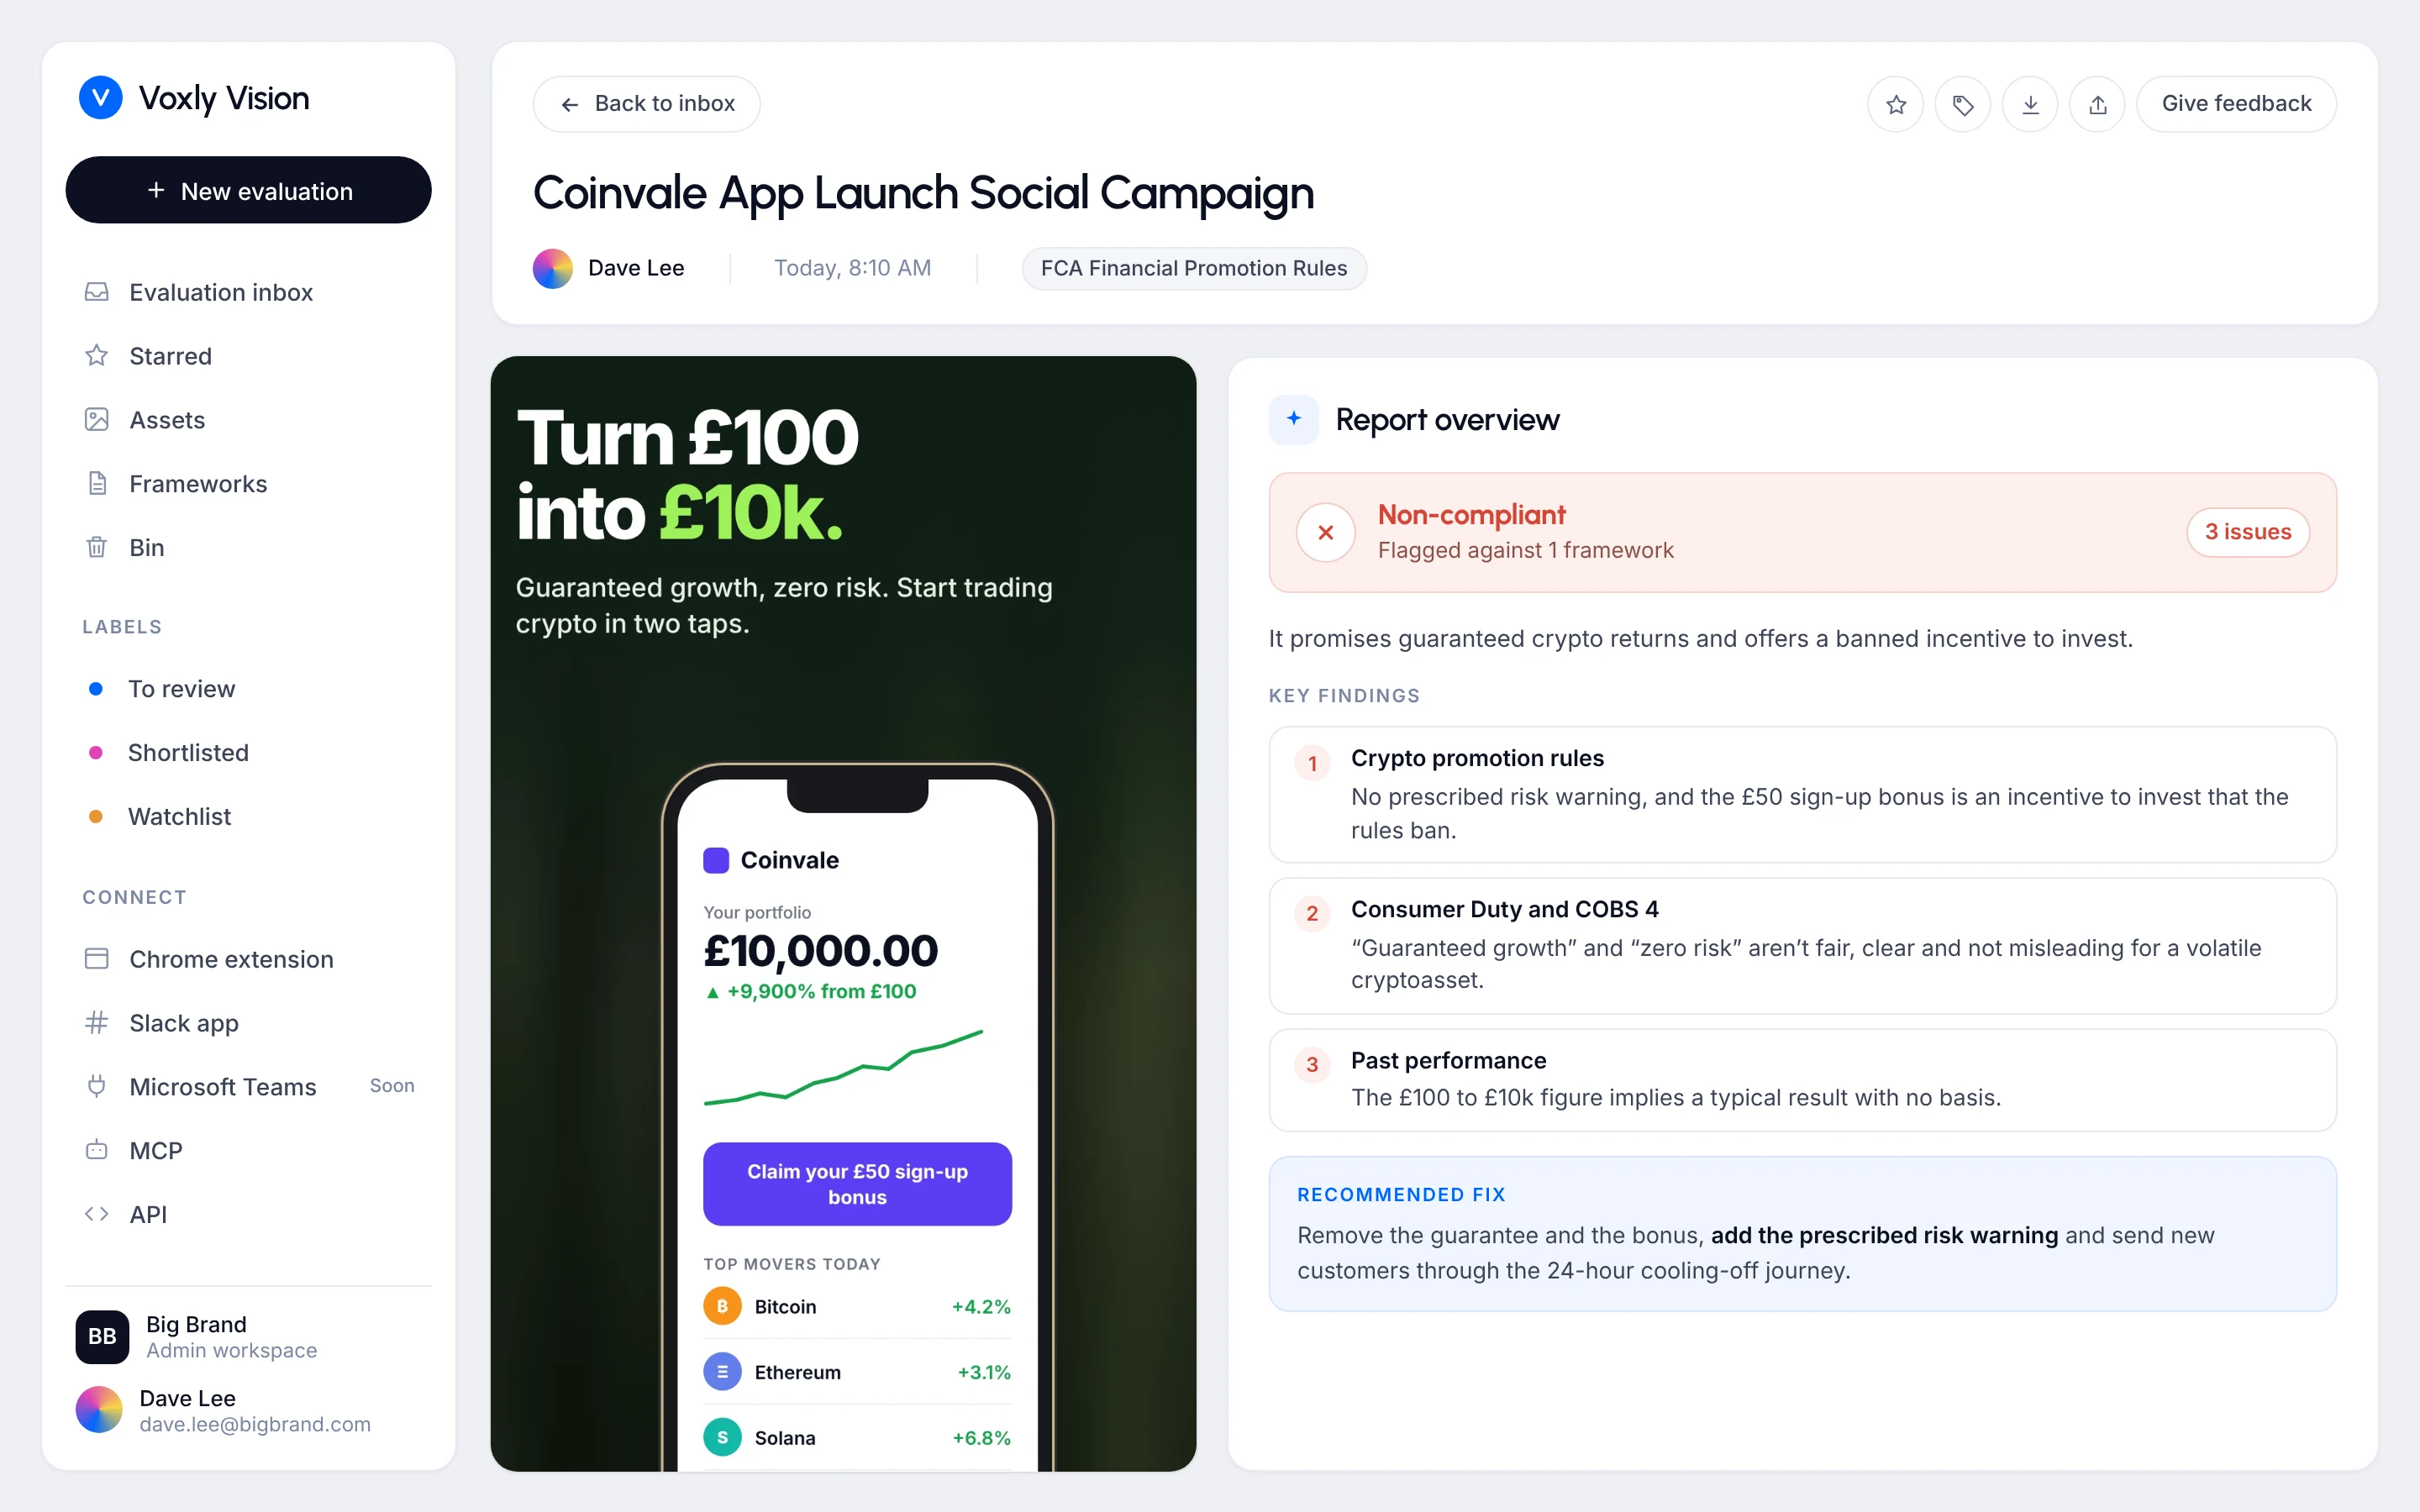
Every report shows an overall verdict, the rules at stake and a recommended fix. For banks, Voxly Vision checks savings and current account promotions for clear rate information before they go out.
Recent rulings
FCA cash savings review
Findings · 18 Sep 2024
Banks sent over 100 million savings messages in 2023, but the effectiveness of repeated generic messages was limited. Some failed to explain the customer's current rate or the benefit of switching.
Rules: BCOBS 2 Communications, Consumer Duty
Frequently asked questions
What does BCOBS 2 cover?
How banks and building societies communicate about and promote current and savings accounts, including interest rates and changes.
How does it relate to the Consumer Duty?
They work together — BCOBS 2 sets banking-specific rules, and the Consumer Duty adds an outcomes-based understanding standard.
Do banks have to tell me about rate changes?
Yes, but that duty sits in BCOBS 4, which covers notices about rate changes and expiring introductory rates. BCOBS 2 covers how rates are shown in promotions and summary boxes.
Who enforces BCOBS 2?
The FCA.