 Voxly Vision

Does this apply to me?
MCOB 3A applies to firms promoting regulated mortgage and home finance products, including:
- Mortgage lenders and brokers
- Equity release and later-life lending providers
- Intermediaries advertising home finance
It is enforced by the FCA, which has paid close attention to equity release and later-life lending promotions in particular.
Key rules
The main requirements:
- Risk warnings where required.
- Representative examples presented clearly.
- Balanced claims about cost — no understating the long-term picture.
- Clear, fair and not misleading throughout.
Common breaches
Where promotions fall short:
- Understating the cost of borrowing, especially over the long term.
- Missing or weak risk warnings.
- Unbalanced claims about equity release.
How Voxly Vision checks an ad against this code
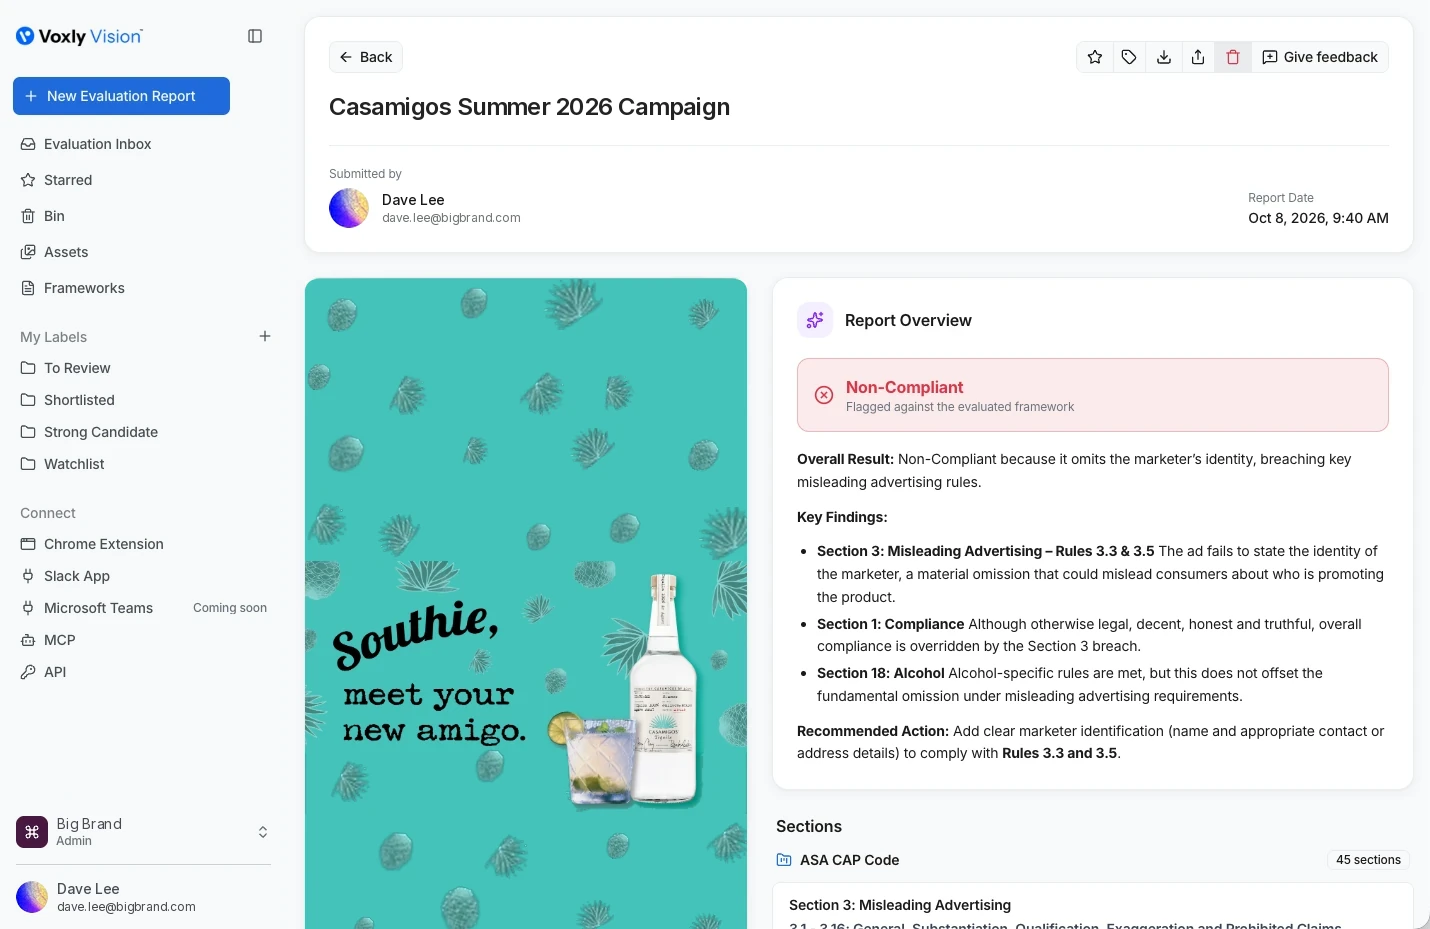
Every report shows an overall verdict, the rules at stake and a recommended fix. For mortgage and equity release ads, Voxly Vision flags missing risk warnings and claims that understate the long-term cost.
Recent rulings
Later-life mortgage firms
~400 promotions removed · Sep 2023
After reviewing equity release and later-life lenders, the FCA got almost 400 misleading promotions taken down or changed and pushed the biggest firms to fix their advice.
Rule: MCOB 3A Promotions
Frequently asked questions
What does MCOB 3A cover?
Mortgage and equity release advertising, including risk warnings, representative examples and balanced cost claims.
Why is equity release a focus?
Later-life and equity release products carry long-term costs and risks, so the FCA scrutinises their promotions closely.
Do mortgage ads need risk warnings?
Yes, where required under MCOB 3A, alongside clear representative examples.
Who enforces MCOB 3A?
The FCA.