 Voxly Vision
The problem
Financial promotions sit under the FCA, and the stakes are higher than a ruling. Promote without authorisation or approval and it can be a criminal offence. Finfluencers have already been convicted.
The Consumer Duty raised the bar again. It's no longer enough to include the risk warning. Customers have to actually understand it.
Meanwhile your marketing team wants to move at social speed, and every asset queues for compliance sign-off.
What we check
Every asset is checked against the rules for your products:
- FSMA section 21 and the Consumer Duty: fair, clear and not misleading, and actually understood.
- CONC 3 for credit and BNPL, including representative APR.
- COBS 4, MCOB 3A, ICOBS 2.2 and BCOBS 2 for investments, mortgages, insurance and banking.
- Crypto promotion rules: risk warnings, cooling-off and banned incentives.
- Your own house standards: required wording, disclaimers and tone.
You get a verdict, the rules at stake and a recommended fix, in under a minute.
How Voxly Vision checks an ad
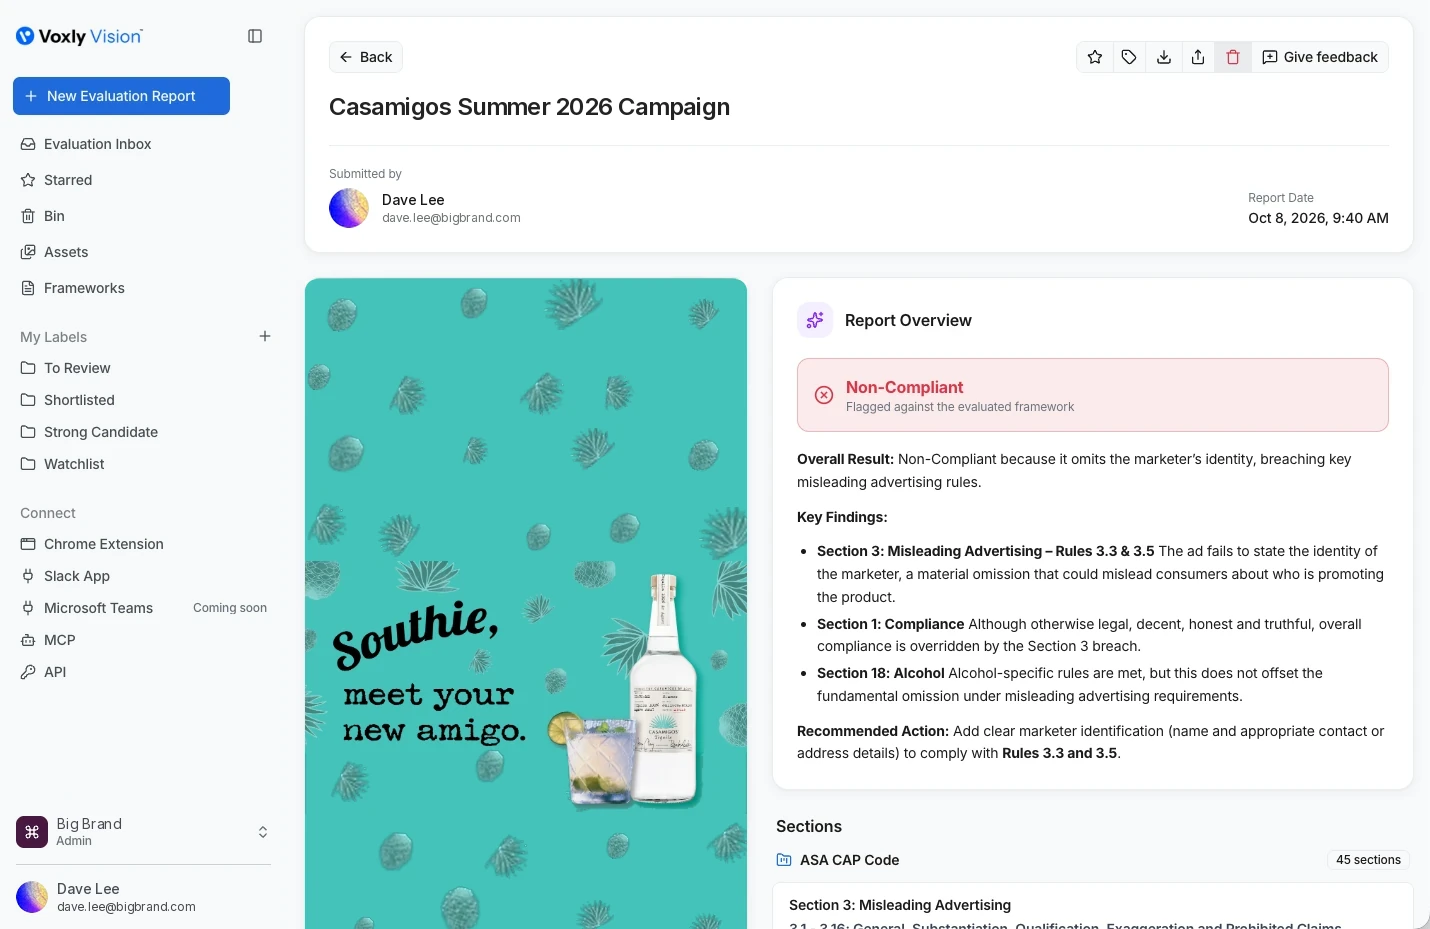
Every report shows an overall verdict, the rules at stake and a recommended fix, giving your team a record of how each promotion was reviewed.
Regulations we check
Latest rulings
No rulings write-ups for this sector yet. Catch every week's rulings on the blog.
Who it's for
Frequently asked questions
Does Voxly Vision approve financial promotions?
No. Approval stays with your authorised people. Voxly Vision does the first pass so they review cleaner drafts, faster.
Can it check finfluencer content?
Yes. Check creator posts before they go live, including whether they count as a financial promotion.
Can it check against our own standards?
Yes. We load your house rules alongside the FCA requirements.
Does it keep a record of reviews?
Every check produces a report you can keep with the asset.