 Voxly Vision
Does this apply to me?
ICOBS 2.2 applies to firms carrying out insurance distribution, including:
- Insurers and insurance brokers
- Intermediaries and comparison services
- Anyone promoting insurance products
It is enforced by the FCA and works alongside the Consumer Duty's understanding outcome.
Key rules
The core requirement:
- Clear, fair and not misleading communications and promotions.
- Make cover and exclusions understandable — customers should know what they're buying.
- Be transparent on price.
- No burying of key limitations.
Common breaches
Typical failings:
- Unclear exclusions — customers unaware of what isn't covered.
- Misleading impressions about the scope of cover.
- Opaque pricing.
How Voxly Vision checks an ad against this code
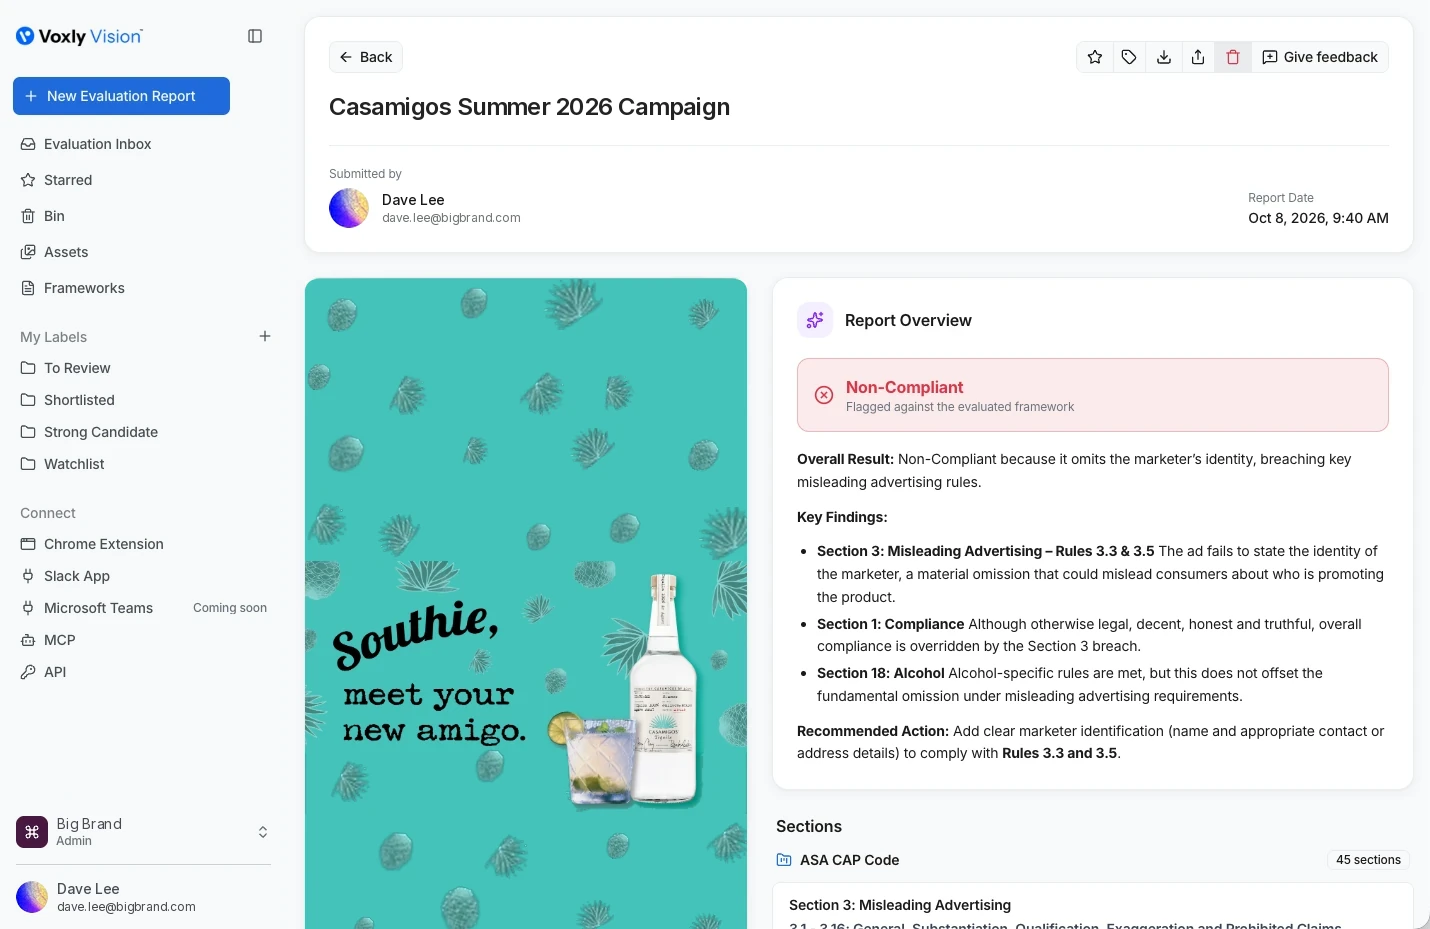
Every report shows an overall verdict, the rules at stake and a recommended fix. For insurance ads, Voxly Vision flags exclusions buried in small print and headlines that overstate what's covered.
Recent rulings
FCA promotions data, Q4 2024
3,697 amended · Feb 2025
In late 2024, FCA action got 3,697 promotions amended or withdrawn across 78 firms. Insurance and protection made up 6% of that workload, ahead of retail banking.
Rule: ICOBS 2.2 Clear, fair and not misleading
Frequently asked questions
What does ICOBS 2.2 require?
That insurance communications and promotions are clear, fair and not misleading, so customers understand cover, exclusions and price.
What's the biggest insurance marketing risk?
Ambiguity about what's actually covered — particularly exclusions customers don't realise apply.
Does the Consumer Duty apply too?
Yes. ICOBS 2.2 works alongside the Consumer Duty's understanding outcome.
Who enforces ICOBS 2.2?
The FCA.