 Voxly Vision
Does this apply to me?
The Consumer Duty applies across FCA-regulated financial services firms, covering:
- Banks, insurers, lenders and investment firms
- Their communications, marketing and customer journeys
- Product design, pricing and support as well as promotion
It is enforced by the FCA and judged on outcomes: did customers actually understand, and were they able to act in their own interest?
Key rules
The consumer understanding outcome in practice:
- Communicate for understanding, not just compliance — plain, timely, relevant information.
- Test and evidence that communications work.
- Outcomes over disclosure — ticking a disclosure box isn't enough.
- Tailor to the audience, including vulnerable customers.
Common breaches
Where firms fall short:
- Dense, jargon-heavy communications customers don't grasp.
- Generic mass mailings that don't help people act.
- Failing to evidence that communications achieve understanding.
How Voxly Vision checks an ad against this code
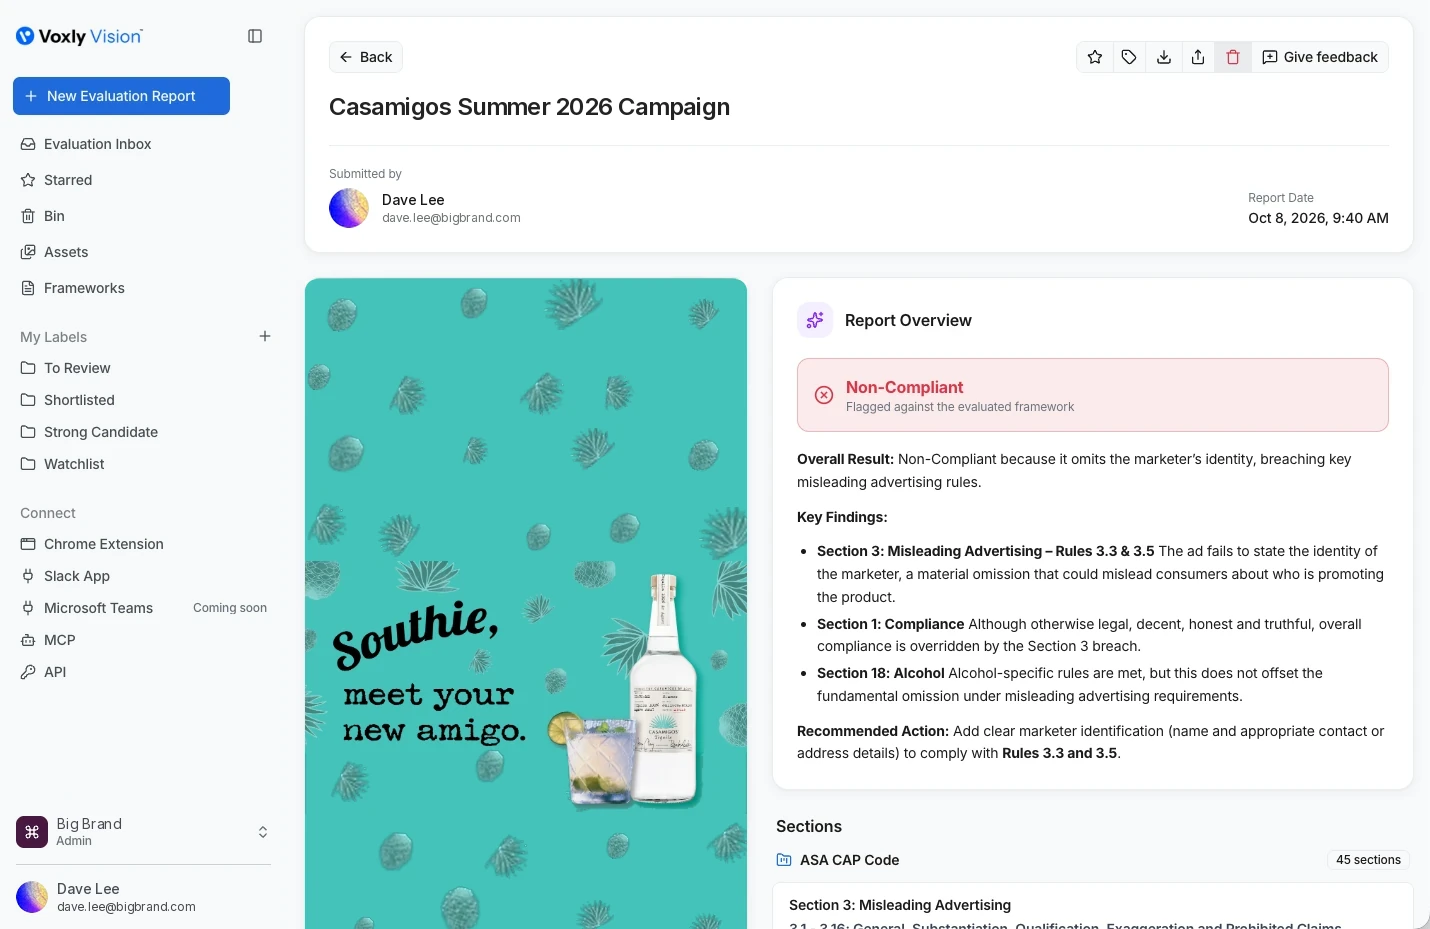
Every report shows an overall verdict, the rules at stake and a recommended fix, giving your team a record of how each communication was reviewed for customer understanding.
Recent rulings
FCA enforcement pipeline
11 investigations · 7 Jul 2026
Three years in, the FCA has opened 11 Consumer Duty investigations across insurance, pensions, investments and claims firms, and intervened 382 times in the past year.
Rule: PRIN 2A.5 Consumer understanding
Frequently asked questions
What is the Consumer Duty?
An FCA standard requiring firms to deliver good outcomes for customers, including communicating so customers genuinely understand.
How is it different from old disclosure rules?
It's judged on outcomes, not on whether a disclosure was made — understanding has to actually happen.
Does it affect marketing?
Yes. Every communication has to support customer understanding and good decisions.
Is the FCA enforcing it?
Yes — it has opened multiple investigations and intervened hundreds of times.